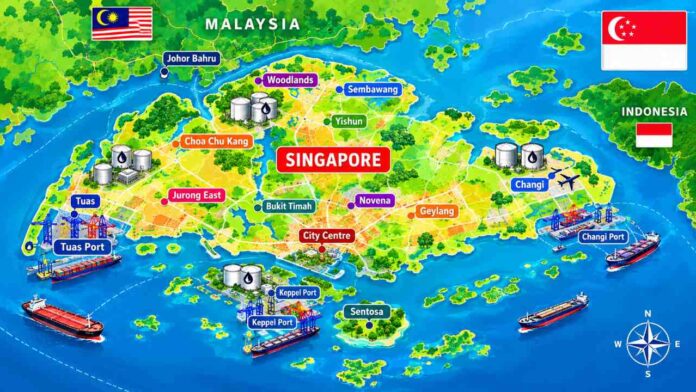

Singapore’s marine-fuel market is showing signs of settling into a new operating pattern after months of disruption caused by the conflict around the Strait of Hormuz, with traders and ship operators increasingly relying on alternative supply channels to keep vessels bunkered.
The improvement does not mean that the underlying energy shock has disappeared. Instead, the shipping and bunker industries appear to have adjusted to a prolonged period in which some conventional Middle Eastern supply routes remain difficult to use. Industry representatives speaking at the Asia Pacific Petroleum Conference (APPEC) in Singapore said the acute shortage experienced earlier in the year had eased, although prices and procurement risks remain considerably higher than before the conflict.
Reuters report on the marine-fuel market
The Strait of Hormuz remains central to the problem. The waterway is one of the world’s most important energy corridors, connecting the Persian Gulf with international markets. Disruption there has affected the movement of crude oil and petroleum products while forcing companies to reassess where they obtain the components required to manufacture marine fuels.
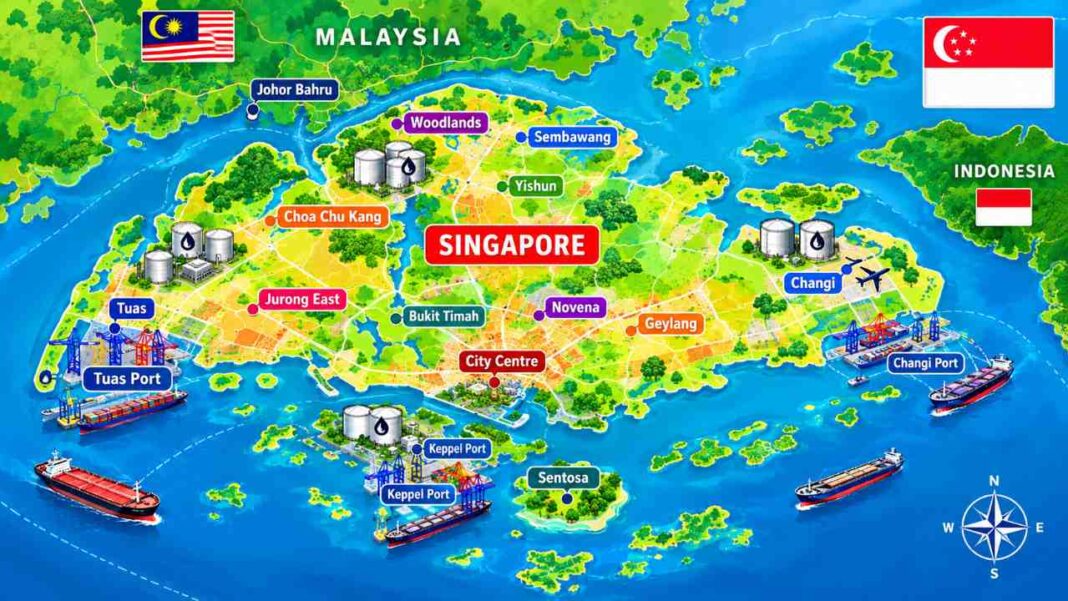
Singapore, one of the world’s largest bunkering centres, has consequently become an important indicator of how the shipping industry is absorbing the shock.
From shortage fears to supply flexibility
The market’s adjustment has been driven partly by the availability of alternative barrels. Traders have been searching beyond traditional Middle Eastern sources, while refiners, suppliers and shipowners have changed purchasing strategies to reduce dependence on individual supply routes.
According to industry participants quoted at APPEC, bunker buyers are currently able to obtain marine fuel, although obtaining particular grades and blending components can be more complicated. This distinction is important: the immediate concern has shifted from a straightforward lack of fuel to the uncertainty surrounding the availability, price and specification of individual feedstocks.
That change has allowed Singapore’s bunker industry to continue functioning despite the disruption.
The recovery is also reflected in the behaviour of prices. Reuters reported that Singapore’s very-low-sulphur fuel oil (VLSFO) prices remained more than 60% above their pre-war levels, even after retreating from the peak reached in March 2026. The figures underline how an improvement in physical availability does not necessarily translate into a return to normal pricing.
Shipping adapts to a different energy map
For shipowners, the changing bunker market is part of a wider transformation in voyage planning. Longer routes, altered refuelling patterns and higher transportation costs have become increasingly important considerations as companies seek to avoid exposure to the most vulnerable parts of the Middle Eastern supply chain.
The continuing disruption has also encouraged greater interest in alternative sources of crude and refined products. Tanker operators are travelling farther to move replacement supplies, while traders are attempting to balance inventories across different regional markets.
Recent Reuters reporting has highlighted the wider consequences for crude transportation, with tanker demand and freight rates rising sharply as companies redirect oil flows away from traditional Middle Eastern routes.
Singapore’s position gives it an additional advantage. Its established refining, storage, trading and bunkering infrastructure allows suppliers to respond relatively quickly when the source of a particular cargo changes. That flexibility is becoming increasingly valuable in an environment where shipping companies cannot assume that previously dependable supply routes will remain available.
Fujairah faces a tougher environment
The contrast with other major bunkering locations is notable. Reuters reported that bunker activity in Fujairah, another important marine-fuel hub, had fallen to around 40% of its pre-war level, while Singapore’s operations remained comparatively steady.
That difference illustrates the importance of geography. Singapore is far from the immediate conflict zone and has access to a broad network of Asian refining and trading markets. Fujairah, by contrast, sits much closer to the Gulf supply system affected by the disruption.
Nevertheless, Singapore is not insulated from the consequences. Higher procurement costs, longer voyages and uncertainty over blending components can still feed through to bunker prices and ultimately to shipping expenses.
Relief, but not a return to normal
The current market therefore represents adaptation rather than resolution. Industry participants have demonstrated that global shipping can reorganise fuel procurement when established supply channels become unreliable. Yet the cost of that flexibility remains significant.
There is also little certainty that the present equilibrium will remain stable. Even when sufficient fuel is available overall, a sudden interruption affecting a particular refinery, blending component, tanker route or regional inventory could produce another temporary squeeze.
The situation has become more complicated as other energy routes face pressure. Recent disruptions involving Saudi oil infrastructure have added another layer of uncertainty to global crude flows, although oil prices subsequently eased as concerns about some supply interruptions diminished.
For Singapore’s maritime sector, the lesson is increasingly clear: maintaining reliable bunker availability is no longer simply a question of having sufficient fuel stored nearby. It depends on a much wider network of refineries, traders, tankers, blending facilities, storage terminals and alternative shipping routes.
As the Hormuz disruption enters a prolonged phase, that network is being tested in real time. Singapore’s marine-fuel market has so far demonstrated considerable resilience, but the elevated prices and continuing geopolitical risks mean that shipping companies are likely to remain cautious.
The immediate supply squeeze may have eased. The larger challenge — operating a global maritime economy while one of its most important energy corridors remains unreliable — is far from over.