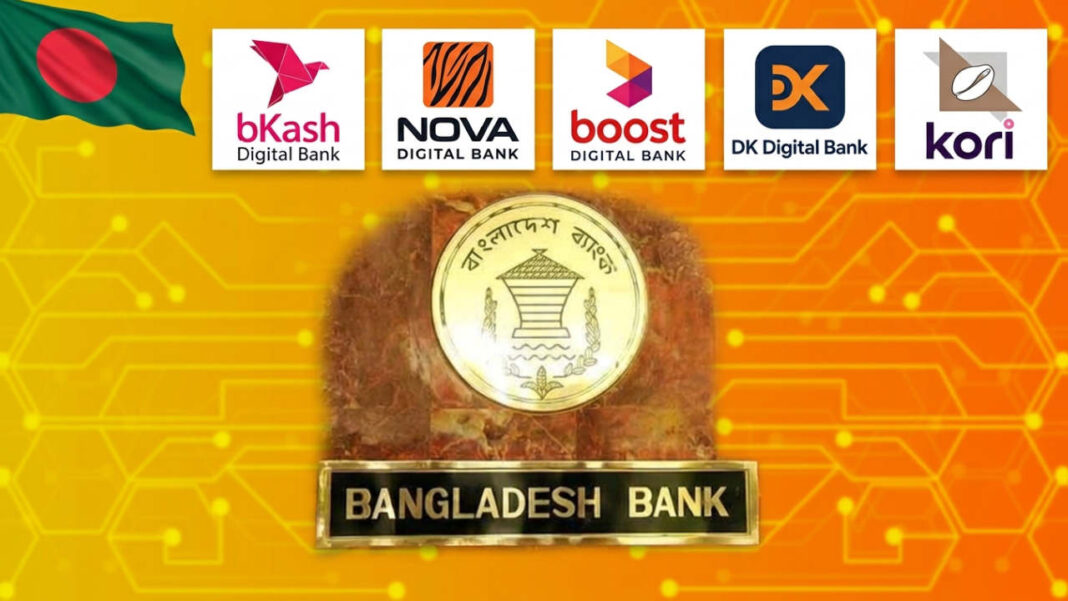

Bangladesh (Commonwealth Union)_ Bangladesh Bank has given preliminary approval to five companies to establish digital banks, marking a major step towards expanding technology-based financial services in the country. The central bank’s board approved the proposals at a meeting chaired by Governor Mostaqur Rahman. The approved ventures include projects backed by bKash, Axiata Limited, Bhutan’s DK Bank, VEON and Square Group. The regulator will now issue Letters of Intent (LOIs) to the five applicants. The LOIs do not amount to full banking licences. Bangladesh Bank spokesperson Arief Hossain Khan said the companies must first meet a number of regulatory requirements before they can begin operations.
Also read: How three Indian-origin researchers broke into OpenAI’s backyard: The hack that shook the AI world!
The five approved ventures are Digital Banking of Bhutan, backed by DK Bank; bKash Digital Bank, supported by bKash shareholders; Nova Digital Bank, backed by VEON and Square Group; Boost Digital Bank, sponsored by Axiata Limited, the parent company of Robi; and Kori Digital Bank. The decision follows more than three years of discussions, policy changes and assessments surrounding digital banking in Bangladesh. The central bank had invited applications during the interim government period, receiving proposals from 13 organisations. The applicants included major business groups, mobile operators, microfinance institutions and mobile financial service providers.
Bangladesh Bank assessed the applicants on several factors, including their banking experience, financial strength, technological capacity, cybersecurity arrangements and ability to meet regulatory requirements. Eight applicants were initially considered eligible for final consideration, but the board eventually selected five for preliminary approval. Additionally, digital banks will operate differently from traditional banks. Under Bangladesh Bank’s guidelines, they will not be allowed to establish physical branches, sub-branches or agent outlets. They will also not operate their own ATM, CDM or CRM networks or offer over-the-counter services. Instead, they will depend on existing banking infrastructure, mobile financial services and shared ATM networks.
The banks will also be permitted to handle eligible inward remittances, provided they follow regulatory requirements and maintain proper digital records. However, they will not be allowed to finance foreign trade or provide loans to medium and large industries. Bangladesh Bank said a properly regulated digital banking sector could make financial services more efficient and accessible. It also stressed the importance of technology-based risk management, cybersecurity and customer protection.
Separately, the central bank warned the public about 22 online payment aggregator platforms operating without approval. Bangladesh Bank said these platforms were providing payment services without the required licences and advised people not to use them. The regulator said operating an unlicensed payment service is illegal under the Payment and Settlement Systems Act, 2024, and can lead to penalties. It urged the public to avoid transactions through the identified platforms to protect their money and reduce legal risks.